|
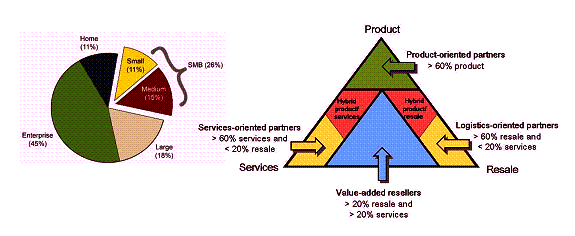
IDC's Canadian Small and Medium Business and Channel Partner Strategies service offers intelligence and expertise to help clients develop, implement, support, and manage effective SMB market and channel partner strategies. It also provides a comprehensive view of the SMB ICT market and the value of the channel in the market overall. This service is designed to assist vendors in understanding and segmenting the SMB market and channel partner ecosystem more effectively, and in creating better go-to-market strategies, including identifying key areas of opportunity, critical business and ICT spending priorities and trends, and the most effective channel strategies.
|
|
This service covers the following segments of the Canadian SMB and channel markets:
- Analysis by market type (hardware, software, services, and telecom)
- Analysis by business size
- Analysis by geography
- Analysis by partner business model (i.e., VARs, SIs, ISVs)
- Industry practices
|
|
Throughout the year, this service will address the following topics:
- ICT expenditures by Canadian SMBs
- Channel business across IT markets (hardware and software)
- Business and technology drivers/inhibitors in the SMB market
- Vendor perceptions and ICT buying behavior of SMBs
- Channel strategy/program development and execution
- SMB market and channel partner trends
- SMB segmentation
- SMB industry views
|
|
Our research addresses the following issues that are critical to your success:
- What is the size of the ICT opportunity by SMB segments and technology?
- What are the critical SMB business and ICT spending priorities?
- How can vendors better segment to more effectively target the SMB market?
- What are the key channel partner strategies, programs, and industry practices for vendors to consider?
- What are the leading trends/challenges impacting the channel, and how do they affect vendor relationships?
|
 |
| Source: IDC |
|
|
|
|
IDC's Canadian Small and Medium Business and Channel Partner Strategies service examines how information and communications technology vendors are positioning themselves to compete in this large and diverse market. This service reviews the strategies, market positioning, and future direction of several providers to the Canadian SMB market, including:
Accenture, Avnet, Bell, CA, CGEY, CGI, Cisco, Dell, Deloitte, EMC, Fujitsu, HP, IBM, Intel, KPMG, Lenovo, Microsoft, MTS-Allstream, Nortel, Novell, Oracle, PwC, Rogers, SAP, Sun, Symantec, Synnex, Tech Data, TELUS, and Toshiba.
|
|
This service focuses on the following core research. In addition to the insight provided in this service, IDC may conduct additional research on specific topics, or emerging market segments, via research offerings that require additional IDC funding and client investment.
|
| ICT Spending Priorities |
|
These studies assess ICT investment priorities for hardware, software, services, and telecom spending by SMB sector and select industries.
|
| SMB Segmentation Strategy |
|
This research examines new methods of segmenting the SMB market in Canada, with guidance for vendors on strategies and market positioning.
|
| Canadian SMB Forecast |
|
This research examines the spending on IT by the SMB market in Canada by size segment and technology category over five years.
|
| Canadian Channel Forecast |
|
This research examines channel IT business in Canada by technology category over five years and provides guidance on maximizing the channel opportunity.
|
| Channel Partner Dynamics |
|
This ongoing research of channel partners across Canada identifies key drivers and inhibitors to their businesses and vendor relationships.
|
|
IDC offers a complete market intelligence solution customized to meet your business requirements. The array of products and services available to you includes:
- The opportunity to have your specific questions answered through personal interaction with industry experts who cover the topics and markets in your service
- Around-the-clock access to our market intelligence on idc.com, IDC's personalized Web experience
- A view of the market's future with 12 months of continuous intelligence about its direction and the reasons behind it, along with actionable advice for taking advantage of existing and emerging opportunities
- Special client discount pricing on purchases of research from other services
- Complimentary admission to IDC's annual Directions conference, where you'll hear our latest forecasts and network with IDC analysts and other industry professionals
- Complimentary invitations to monthly executive telebriefings, interactive forums designed to provide you with insights about research and strategies directly from IDC analysts
To find out how our flexible packaging options can meet your specific business needs, please contact your IDC sales executive.
|
|
As a privately held company, IDC believes that our customers are our primary constituency. A large percentage of every revenue dollar is reinvested back into our products, including more analysts, more geographic coverage, and extensive primary research.
Our steady growth over the past 10-plus years reflects our commitment to investing in our customers.
|
|
|