|
IDC's Semiconductors: Personal Computing service provides strategic and tactical analysis for chip suppliers and OEMs in the computing system (desktop, mobile, and x86 server) and hard disk drive (HDD) storage markets. The computer semiconductor market is the largest of all semiconductor markets. It is about to enter another major stage of development characterized by accelerated semiconductor integration, accelerated system segmentation, and more vendor consolidation. By acquiring and integrating intellectual property through a platform, system-oriented approach, large players are consolidating their hold on established segments and are increasing their influence throughout the supply chain, including influence on contract manufacturers and OEMs. This service analyzes technology transitions, vendor positioning, and pricing directions to guide clients to the revenue opportunities.
|
|
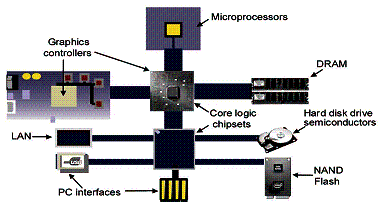
This service covers the following segments of the computing semiconductor market:
- Worldwide desktop PC, mobile PC, and x86 server microprocessor forecast (semiannual)
- PC microprocessor vendor market share (quarterly)
- PC core logic chipset vendor market share (quarterly) by all form factors, CPU vendor supported, and graphics type
- Worldwide hard disk drive semiconductor revenue (annual)
- Hard disk drive semiconductor vendor market share (annual)
- PC supply chain mapping and predictions
- DRAM supply, demand, MB per system, and pricing trends
|
|
Throughout the year, this service will address the following topics:
- PC microprocessors
- PC core logic chipsets and PC graphics processors
- Hard disk drive semiconductors
- DRAM
- Interfaces and technologies
- PC supply chain (semiconductor, ODM, and OEM)
|
|
Our research addresses the following issues that are critical to your success:
- What will be the impact of the major processor vendors' transition to a system-on-chip approach? How fast will higher numbers of processor cores be introduced?
- What are the roadmaps and market strategies for major players such as Intel (processors, core logic), AMD (processors, core logic, and graphics), and Nvidia (graphics)?
- What will be the impact on NAND flash memory in the PC, including NAND caches and solid state disk (SSD) drives?
- Where do processors go when they don't go into PCs, and what new opportunities do non-PC devices represent?
- What will be the penetration rate of new technologies such as DDR III memory, PCI Express, 802.11n, and Serial ATA?
- Which HDD semiconductor market segment is the largest, and which one is driving growth?
|
 |
| Source: IDC |
|
|
|
|
IDC's Semiconductors: Personal Computing service examines how semiconductor vendors are positioning themselves to compete in the computing semiconductor market. This service reviews the strategies, market positioning, and future direction of several providers in the semiconductor market, including:
AMD, Broadcom, Elpida, Hynix, IBM, Infineon, Intel, LSI Logic, Marvell, Micron, Nanya, NVIDIA, Qimonda, Rambus, Samsung, SiS, STMicroelectronics, Texas Instruments, and VIA Technologies.
|
|
This service focuses on the following core research. In addition to the insight provided in this service, IDC may conduct additional research on specific topics, or emerging market segments, via research offerings that require additional IDC funding and client investment.
|
| Worldwide PC Microprocessor Forecast |
|
This semiannual study covers the unit shipments, average selling prices, and revenue of PC microprocessors designed for desktop PCs, mobile PCs, and x86 servers. It segments unit shipments according to the number of cores in the processors.
|
| Worldwide PC Interface and Technology Forecast |
|
This study forecasts the penetration rates of dozens of existing and emerging technologies and interfaces in desktop PCs and mobile PCs. Examples of technologies covered include cellular technology, ultrawideband, integrated graphics, Gigabit Ethernet, PCI Express, trusted platform module, and ExpressCard.
|
| Worldwide Quarterly PC Microprocessor Vendor Shares |
|
This study provides quarterly processor vendor market share overall and in the desktop, mobile, and x86 server segments.
|
| Worldwide Quarterly PC Core Logic Chipset Vendor Shares |
|
This study provides quarterly core logic chipset vendor market share overall and segments results by form factor, processor vendor supported, and graphics support (integrated or discrete).
|
| Mapping the Desktop, Mobile, and x86 Server Supply Chains |
|
This study tracks the flow of PC microprocessors, PC chipsets, and PC motherboards through the PC supply chain to finished desktop PCs, mobile PCs, and x86 servers.
|
| Worldwide DRAM Demand and Supply Analysis |
|
This semiannual study covers major DRAM vendors, providing competitive analysis in key product areas. It also evaluates supply and demand trends, pricing trends, and interface transitions.
|
| Worldwide HDD Semiconductor Forecast and Analysis |
|
This annual study covers the market for HDD semiconductors, including hard disk controllers, read channels, preamps, motor controllers, and SoCs. It analyzes the unit shipments, ASPs, and revenue across all drive form factors and chip types.
|
| Worldwide Hard Disk Drive Semiconductor Vendor Shares |
|
This study provides HDD semiconductor vendor market share overall and in the desktop, mobile, and x86 server segments for SoCs, hard drive controllers, read channels, motor controllers, and preamplifiers.
|
|
IDC offers a complete market intelligence solution customized to meet your business requirements. The array of products and services available to you includes:
- The opportunity to have your specific questions answered through personal interaction with industry experts who cover the topics and markets in your service
- Around-the-clock access to our market intelligence on idc.com, IDC's personalized Web experience
- A view of the market's future with 12 months of continuous intelligence about its direction and the reasons behind it, along with actionable advice for taking advantage of existing and emerging opportunities
- Special client discount pricing on purchases of research from other services
- Complimentary admission to IDC's annual Directions conference, where you'll hear our latest forecasts and network with IDC analysts and other industry professionals
- Complimentary invitations to monthly executive telebriefings, interactive forums designed to provide you with insights about research and strategies directly from IDC analysts
To find out how our flexible packaging options can meet your specific business needs, please contact your IDC sales executive.
|
|
As a privately held company, IDC believes that our customers are our primary constituency. A large percentage of every revenue dollar is reinvested back into our products, including more analysts, more geographic coverage, and extensive primary research.
Our steady growth over the past 10-plus years reflects our commitment to investing in our customers.
|
|
|
|

|
Shane Rau
Program Director, Computing, Networking, and Storage Semiconductors
|
|
|
|
|
|
|
|
|
|