|
The impact of the market forces acting upon the Canadian server market, such as technologies (virtualization and multicore processors), go-to-market strategies, vendor product and pricing strategies, and customer demands, among others, makes targeting the server market opportunities a challenge. IDC's Canadian Quarterly Server Tracker provides a comprehensive view of today's highly consolidated server market, identifying growing market segments for server vendors to align products and sales resources with market demand. This market intelligence service provides a complete understanding of current trends for volume, midrange, and high-end enterprise server markets, uncovering opportunities as they arise with industry-leading analysis and insights to address them. Identifying market trends and technology adoption rates can help a sales force more effectively retire quotas, leading to increased revenue growth and market share. The supply-side research is supported by demand-side and channel resources encompassing all major technologies, price bands, and product lines in the Canadian server market.
|
|
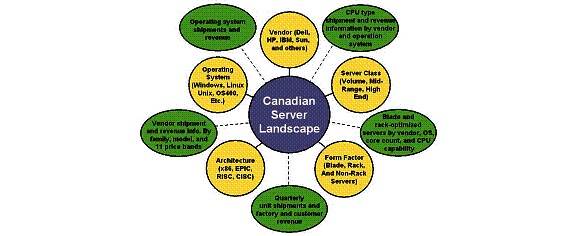
This product covers the following segments of the Canadian server market:
- Vendor (Dell, HP, IBM, Sun, and others)
- Server class (volume, midrange, high end)
- Form factor (blade, rack, and non-rack servers)
- Architecture (x86, EPIC, RISC, CISC)
- Operating system (Windows, Linux, Unix, NetWare, OS/390, OS/400, etc.)
|
|
Throughout the year, this product will address the following topics:
- Quarterly unit shipments and factory and customer revenue
- Vendor shipment and revenue information by family, model, and 11 price bands
- Operating system shipments and revenue
- Granular model-level data for all vendors
- CPU type shipment and revenue information by vendor and operating system
- Blade and rack-optimized servers by vendor, operating system, core count, and CPU capability
- CPU brand-level data at the model level
|
|
Our research addresses the following issues that are critical to your success:
- What is the relative performance of the volume, midrange, and high-end server market segments?
- Which vendor is gaining the most share in the enterprise and volume server segments?
- How much of an impact is Itanium having on the Canadian server market?
- How fast are blade servers being adopted, and which vendors are seeing the most success?
- How fast are Windows-based servers increasing their share of market, and what has been the impact on other servers?
- How will dual-core and multicore CPUs impact the Canadian server market?
|
 |
| Source: IDC |
|
|
|
|
IDC's Canadian Quarterly Server Tracker provides a quantitative assessment of the state of the server market across a variety of metrics, including unit shipments, revenue, price bands, and operating systems. This quarterly tracking product reviews the relative positions of the vendors that shape the market, providing family- and model-level detail. Companies tracked include Acer, Apple, Dell, Gateway, HP, IBM, NCR, NEC, SGI, Sun Microsystems, and Unisys.
|
|
Throughout the year, this product will offer insight into the latest trends impacting the market.
|
| Segmentation |
|
- Vendor
- Family
- Model
- Price band
- Operating system
- CPU capability
- Core count
- CPU architecture and brand
|
| Timely Delivery and Support |
|
- Week 9: Final data delivered by Excel pivot table
- Ten hours per year of telephone inquiry time to support questions regarding data usage
|
| Database Delivery |
|
Nine weeks after the close of each quarter, clients will receive an easy-to-follow email with instructions on how to download the data file from the IDC Tracker Web site.
|
| Inquiry Time |
|
Ten hours of access to an analyst for specific inquiries is included.
|
| Analyst Briefing |
|
This market update and strategy review provides analysis, insights, and in-depth guidance on the server ecosystem with customized advice.
|
 |
| Source: IDC |
|
|
|
|
As a privately held company, IDC believes that our customers are our primary constituency. A large percentage of every revenue dollar is reinvested back into our products, including more analysts, more geographic coverage, and extensive primary research.
Our steady growth over the past 10-plus years reflects our commitment to investing in our customers.
|
|
|