|
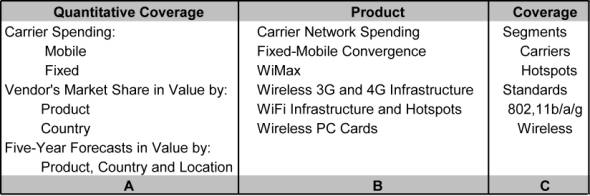
IDC's European Emerging Carrier Infrastructure service provides timely and essential carrier network equipment expenditure figures to companies that need to take advantage of promising business opportunities. Carrier network spending includes fixed and wireless equipment installed by leading carriers such as KPN, TeliaSonera, BT, and Telecom Italia. This service also addresses emerging technologies such as femtocell, picocells, fixed/mobile convergence, and 4G. Furthermore, it looks at the developments of city networks, mesh networking, WiMax, and mobile PC cards. Finally, it considers the development of WiFi at hotspot locations and identifies market opportunities for telecommunications providers, equipment vendors, location owners, and consulting companies. Our research reveals market trends and adoption and vendor market share on a country basis, with studies offering a five-year forecast essential to any business plan.
|
|
This service covers the following segments:
- Fixed and mobile network spending by type of carrier
- 3G, 3G HSPA, 3G HSPA+, 3G LTE, and 4G network equipment infrastructure
- Fixed-mobile convergence
- Wireless technologies: WiFi, mesh networking, WiMax, city wide network, mobile PC cards
- Hotspots: airports, airport lounges, hotels, exhibitioncenters, gas stations, train stations, cafes and restaurants
|
|
Throughout the year, this service will address the following topics:
- Carrier network investment by fixed and mobile network infrastructure
- Analysis of fixed-mobile convergence (FMC) (femtocells, picocells, GAN/UMA, etc.)
- Market drivers, challenges, and equipment forecasts for UMTS and WiFi networks
- Market development and spending of 3G in Western Europe
- Analysis of 4G market developments
|
|
Our research addresses the following issues that are critical to your success:
- How much have KPN, BT, and other providers invested in network equipment in 2006? How much will they invest between 2007 and 2012?
- How will fixed-mobile convergence move forward? What are the new enabling technologies and what challenges will take place?
- How will 4G evolve? What are the network equipment implications?
- What are the leading emerging technologies?
- How many WiFi hotspots are there in Europe today and how many will there be in 2012?
- Which locations are likely to have the most success in offering WiFi services, and why?
- How many 2.5G, 3G, and WiFi PC cards are there today, and how many will there be in 2012?
- How will technologies such as WiFi and mesh networking impact and integrate with the mobile network infrastructure?
|
 |
| Source: IDC |
|
|
|
|
IDC's European Emerging Carrier Infrastructure service examines how fixed and mobile equipment vendors, telecommunications companies, and location owners offering carrier network equipment and emerging technologies services are positioning themselves to compete in the Western European market. This service reviews strategies, market positioning, and future direction of several providers in the market, including:
Equipment vendors: 3Com, Alcatel-Lucent, Aruba, Avaya, Cisco, Ericsson, Intel, iPass, Linksys, Motorola, Netgear, Nomadix, Nokia Siemens Networks, Nortel, and Huawei Proxim.
Main carriers: France Telecom, Deutsche Telekom, KPN, BT, Vodafone, Telecom Italia, Telefónica, Telekom Austria, Belgacom, OTE, Portugal Telecom, Telenor, TeliaSonera, and TDC.
|
|
Throughout the year, this service will offer insight into the latest trends impacting the market. Potential studies include:
|
| Picocell Market Development |
|
The study will analyze the opportunity for picocells in Western Europe. In particular, it will forecast the Western European market for picocell-enabled mobile services in terms of users and respective spending. It will also assess the main developments and discuss drivers and inhibitors, key issues, and challenges in deploying picocells.
|
| 3G Mobile Spending in Western Europe |
|
This document contains 3G market vendor share data for the Western European market. Shares are calculated according to revenue and unit shipments.
|
| Western European 4G Market Development |
|
This study analyzes the competing and prevailing visions and examines the development stage for the fourth generation (4G) of mobile communication infrastructures in Western Europe.
|
| Western European WiFi Hotspot Market Forecast |
|
This study will provide insight into the hotspot concept, key trends, and technological and operational aspects. Forecasts include deployment and opportunity for both equipment and service providers by type of location for 16 countries in Western Europe.
|
| Western European Mesh Networking Forecast and Analysis |
|
This document focuses on the development of mesh networking. It sizes and forecasts the market and includes a review of equipment vendors, market development, market segmentation, and drivers and inhibitors.
|
| Mobile Service Provider Spending |
|
This study will provide figures on network equipment spending by type of service provider. For example, the document shows how much BT, KPN, TeliaSonera, Vodafone, Orange, and others have invested on mobile network equipment.
|
| Western European 2.5G and 3G Combo PC Card Market Analysis |
|
This study will provide information and forecast data on 2.5G and 3G combo PC cards in Western Europe for 2008 to 2012. Topics analyzed will include key trends, market forecast data, and market segmentation. Market forecasts are provided for 16 countries in Western Europe.
|
|
IDC offers a complete market intelligence solution customized to meet your business requirements. The array of products and services available to you includes:
- The opportunity to have your specific questions answered through personal interaction with industry experts who cover the topics and markets in your service
- Around-the-clock access to our market intelligence on idc.com, IDC's personalized Web experience
- A view of the market's future with 12 months of continuous intelligence about its direction and the reasons behind it, along with actionable advice for taking advantage of existing and emerging opportunities
- Complimentary/special admission price to IDC's annual Directions conference, where you'll hear our latest forecasts and network with IDC analysts and other industry professionals
- Complimentary invitations to monthly executive telebriefings, interactive forums designed to provide you with insights about research and strategies directly from IDC analysts
To find out how our flexible packaging options can meet your specific business needs, please contact your IDC account manager.
|
|
As a privately held company, IDC believes that our customers are our primary constituency. A large percentage of every revenue dollar is reinvested back into our products, including more analysts, more geographic coverage, and extensive primary research.
Our steady growth over the past 10 years reflects our commitment to investing in our customers.
|
|
|